

Edit on the Brevik CCS project which has a capacity of up to 400ktpa but is currently only operating at 100ktpa, thank you Hanno Böck for the correction
ProPublic and Drilled Media recently published an article arguing that carbon capture and storage (CCS) is too expensive, has insurmountable land-use concerns, involves too many pipelines, and lacks storage capacity.
They also allude to the fact that the reason we even discuss CCS is because of a decades-long propaganda campaign waged by “big oil” against climate progress. The argument goes that CCS is a specter, held up by fossil interests to justify continuing to use fossil fuels, even though the technology doesn’t work.
Not only is this inaccurate on the merits (CCS does work and its inclusion into models and academia is one of physical necessity, not some shadowy backroom deals), but if you care about climate and emissions, you’d better hope CCS works. Because in the short- to medium-term, it is the cheapest way to limit emissions from the industrial sector.
This is a long one, but the world is complicated.
A Tale of Two Decarbonizations
US emissions in 2022 break down as: transportation 28%, electric power 25%, industry 23%, residential/commercial 13%, agriculture 10%.
Since the US emissions peaked in 2007, the power sector has declined by about 36%. Transportation is down about 8%, which would be even lower if Americans hadn’t decided that pickup trucks count as sedans. Industry is down about 10%, but most of that is due to the shift away from heavy manufacturing rather than per-ton-of-output decarbonization. Rhodium estimates that industrial emissions fell another 1.8% in 2024, again largely due to softer manufacturing output.
The Congressional Budget Office, working from EIA’s Annual Energy Outlook, projects US manufacturing emissions to rise 17% from 2024 to 2050, while power sector emissions fall 51% and transport sector emissions fall 7%. By 2030, on those projections, manufacturing will emit more than the power sector. We are moving towards a future with a very low-emission grid and very low-emission cars, yet we are nowhere near net-zero.
Why? Because the things that worked for power and transport (cheaper solar, cheaper batteries, an EV that just costs less to own) don’t translate to making physical stuff.
What are industrial emissions?
Industry is a convenient single word that encompasses hundreds of different processes. When people say “hard-to-abate sectors,” they usually mean a specific (and globally significant) handful:
Cement: ~7-8% of global CO2 emissions. About half of those emissions come from a chemical reaction (calcination, in which limestone releases CO2), and another ~40% from burning fuel to drive that reaction at ~1,450°C.
Steel: ~7-9% of global CO2. The dominant blast-furnace route uses coking coal not just for heat but also as the chemical reductant that removes oxygen from iron ore. About two tons of CO2 per ton of crude steel in the BF-BOF route.
Chemicals and petrochemicals: ~5-6% of global CO2. Plastics, fertilizers, solvents, fibers. The challenge is that oil isn’t burned for most of these; it’s used as an input, and the carbon in the hydrocarbons is the product.
Aluminum, glass, paper, refining: smaller individually but each non-trivial, and each with its own physical constraints.
Roughly two-thirds of industrial energy use goes to heat, and roughly a quarter of all industrial CO2 emissions don’t come from energy at all. These are called “process emissions” and are baked into the chemical reactions to make various products. The clearest example is when we create cement; we have to break down limestone. This process, called calcination, emits CO2, and it doesn’t matter whether the energy we use to do it is renewable or fossil-based.
These are key distinctions to keep in mind: energy emissions vs. process emissions vs. feedstock emissions. Renewables can, in principle, address the first but not the second or the third.
Bending the Industrial Curve, or Not
There are three structural reasons that solar, wind, and batteries can’t decarbonize industry the way they’re decarbonizing the grid.
Reason 1: A lot of the CO2 isn’t from energy at all
Cement is the cleanest example. Even if you ran a cement kiln on 100% clean electricity (meaning the fuel you put into the facility and kiln), you’d still emit roughly half of the CO2 per ton of cement, because the limestone is literally emitting CO2 as you calcinate it. CaCO3 → CaO + CO2.
The only ways to address process emissions are: (a) capture and store the CO2 (CCS), (b) change the feedstock so the chemistry doesn’t release CO2 in the first place (Sublime’s electrochemical route, Brimstone’s calcium silicate rock route, both discussed below), or (c) use less cement (better design, blended cements, alternative binders). None of those involves a solar panel or a wind turbine.
Steelmaking has the same flavor of problem. In a blast furnace, coking coal is both a fuel and a reductant (the chemical that removes oxygen from iron). Replacing the heat isn’t the challenging part. Replacing the reductant requires either hydrogen (chemically reducing iron with H2 instead of carbon) or direct electrochemistry (Boston Metal’s molten oxide electrolysis). Both are technically possible. Neither runs on solar panels in a meaningful way today.
Ammonia (the basis for nitrogen fertilizer, which feeds roughly half the planet) is the same story. Hydrogen is the feedstock, and ~95% of the world’s hydrogen still comes from steam methane reformation:
The Steam Methane Reforming reaction: CH4 + H2O (+ heat) → CO + 3H2.
Water Gas Shift Reaction: CO + H2O → CO2 + H2 (+ small amount of heat).
CO2 is a byproduct of producing hydrogen, not of generating power.
Reason 2: High heat is hard to make with renewables
Two-thirds of industrial energy is heat. The temperature profile is roughly:
Low-temperature (<200°C), about 30% of industrial heat demand. Food, paper, light chemicals, pharma. Heat pumps are great alternatives for this, and modern industrial heat pumps from MAN Energy Solutions, Mayekawa, and GEA, as well as start-ups like AtmosZero, can reach 150-200°C at 100+ MW thermal scale.
Medium-temperature (200-500°C), about 20%. Doable with electric boilers and resistance heating, increasingly with heat pumps as the tech matures.
High-temperature (>500°C, up past 1,600°C for steel and ~1,450°C for cement), about 50%. This is where you run out of off-the-shelf electric options, and where the few that exist (electric arc furnaces, plasma torches, electrified crackers being piloted by BASF/SABIC/Linde) become prohibitively expensive at commodity scale.
US industrial natural gas sells to industrial users for roughly $3-5/MMBtu. To compete on a delivered-heat basis, electricity needs to cost something like $20-30/MWh on a 24/7 firm basis (because heat pumps are efficient, but resistance heating isn’t, and you can’t shut down a steel mill when the sun goes down). For most of the country, even cheap renewables-plus-storage don’t get there yet. They may eventually, but they don’t today.
Reason 3: Industry runs on capital cycles that the energy transition can’t shortcut
A modern cement plant costs ~$500M-$1B, runs 40-50 years, and operates on margins that often sit in the high single digits. A blast furnace runs ~20 years between relines (a rebuild that consumes hundreds of millions of dollars). An ethylene cracker is a multi-billion-dollar facility built to last decades.
You can’t tell a plant operator running on 6% margins to rip out their kiln to install something that doesn’t yet have a commercial-scale operating reference. They (rationally) wait until the technology is proven and the economics work, which is almost never until policy or customer demand pulls them.
Compare to the power sector, where a coal plant can be retired and replaced with a gas plant or a wind farm by a different developer entirely. The decision to build new capacity is made at the project level, and the marginal economics of new clean generation now beat those of running existing coal in most US markets. In industry, the equivalent move (shut down a cement plant, build a Sublime plant, sell the same cement at the same price) doesn’t work because the new technology is more expensive and the product is fungible. There’s no industrial equivalent of “renewables win on price.”
The Frontier Tech
There’s no shortage of promising industrial decarbonization technology. The real challenge is getting these technologies through development, down the cost curve, and into competition with fossil fuels as soon as possible.
A non-exhaustive list:
Cement (electrochemical and alternative-feedstock routes). Sublime Systems uses electrolysis to extract calcium hydroxide from non-carbonate rocks at room temperature, thereby avoiding calcination. They run a 250 ton-per-year pilot in Somerville, MA, and were building a 30,000 t/y commercial plant in Holyoke. Brimstone uses calcium silicate rocks instead of limestone and would coproduce alumina (a critical mineral). Their DOE OCED awards were $189M and $87M, respectively.
Both of those DOE awards were canceled by the second Trump administration in mid-2025. Sublime paused construction on Holyoke and laid off 10% of its workforce in December 2025, then laid off two-thirds of its remaining workforce in March 2026 as appeals to the DOE stalled. The company is pursuing private capital plus customer offtakes (Sublime has a Microsoft carbon credit deal; Brimstone has an Amazon offtake). For perspective: global cement production is ~4.0 billion tons per year, so even Brimstone’s 140,000 t/y demo would be 0.0035% of global supply.
Steel (hydrogen DRI and electrochemical routes). The flagship is Stegra (formerly H2 Green Steel) in Boden, Sweden, building the world’s first large-scale hydrogen-based DRI-EAF plant with a 700 MW on-site electrolyzer. The plant nearly ran out of cash in late 2025, was rescued in April 2026 by a €1.4B Wallenberg-led financing round, and is now targeting full hydrogen-based production in 2027 at 2.5 Mt/y (eventually 4.5 Mt/y, vs. ~1.85 Gt of global crude steel). SSAB/LKAB/Vattenfall’s HYBRIT in northern Sweden is similar in concept and somewhat further behind on permitting.
Meanwhile, ArcelorMittal walked away from green-hydrogen DRI conversion at its Bremen and Eisenhüttenstadt plants in June 2025, forfeiting €1.3B in approved German government subsidies and citing the lack of competitive green hydrogen supply. Boston Metal (also MIT) aims to license its molten oxide electrolysis process starting in 2026, but at the lab scale it’s smelting iron in cells the size of a phone booth. Its commercial play is starting with niche alloys before tackling carbon steel.
Petrochemicals (bio-naphtha, e-naphtha, electric crackers). Bionaphtha (a coproduct of HVO biofuel production, which itself relies on used cooking oil and animal fats) is a “drop-in” feedstock that companies like Borealis, INEOS, BASF, and SABIC are now blending into existing crackers. The constraint is supply: bionaphtha is not a primary product; it’s a coproduct of renewable diesel and SAF production, so its availability is capped by demand for those fuels. E-naphtha (produced from captured CO2 and green hydrogen via Fischer-Tropsch) has been technologically demonstrated but remains cost-prohibitive at scale. Mechanical and chemical recycling help, but only ~9% of global plastic is currently recycled.
BASF, SABIC, and Linde jointly fired up the world’s first large-scale electric steam cracker at Ludwigshafen in April 2024, and Dow and Shell are piloting another. It is great to see these early-stage projects, and we should continue to support them with private offtake and government funding, but they’re also one or two orders of magnitude away from petrochemical commodity scale.
The same pattern emerges from nearly all the non-fossil pathways for heavy industry. The technology exists, demonstrations exist, the scale-up to global-commodity capacity does not. And the “green premium” (the extra a customer has to pay to get a low-carbon version of the same product) is not being absorbed by the market. This will become increasingly difficult as power prices rise and fiscal headroom is constrained by the war (in the US). Some low-carbon steel indices saw their premiums fall ~50% in early 2026 as buyers balked.
The Cost Picture, By Commodity
The hardest thing to internalize about industrial decarbonization is the precise shape of the cost gap.
These are bulk commodities traded internationally. Steel, cement clinker, ammonia/urea, and ethylene/polyethylene all move across borders at scale. At the moment, there is little reason why a producer or buyer of any industrial material should care about embodied emissions. This, of course, changes somewhat with the carbon border adjustment mechanism in Europe. They care about $/ton. If the local clean producer charges 30% more, the buyer imports from somewhere that doesn’t.
Producers operate on slim margins. EBITDA margins in commodity steelmaking and bulk chemicals routinely sit in the 5-15% range. Cement is similar. A 20-40% cost premium for a low-carbon version isn’t tenable.
Every cost range referenced below is wide because it depends on local feedstock prices (natural gas, coking coal, naphtha, hydrogen, iron ore, electricity), capex assumptions, and any carbon price. The numbers shouldn’t be read as precise. They should be read as showing the size of the gap.
Cement
Global production ~4.0 Gt/year.
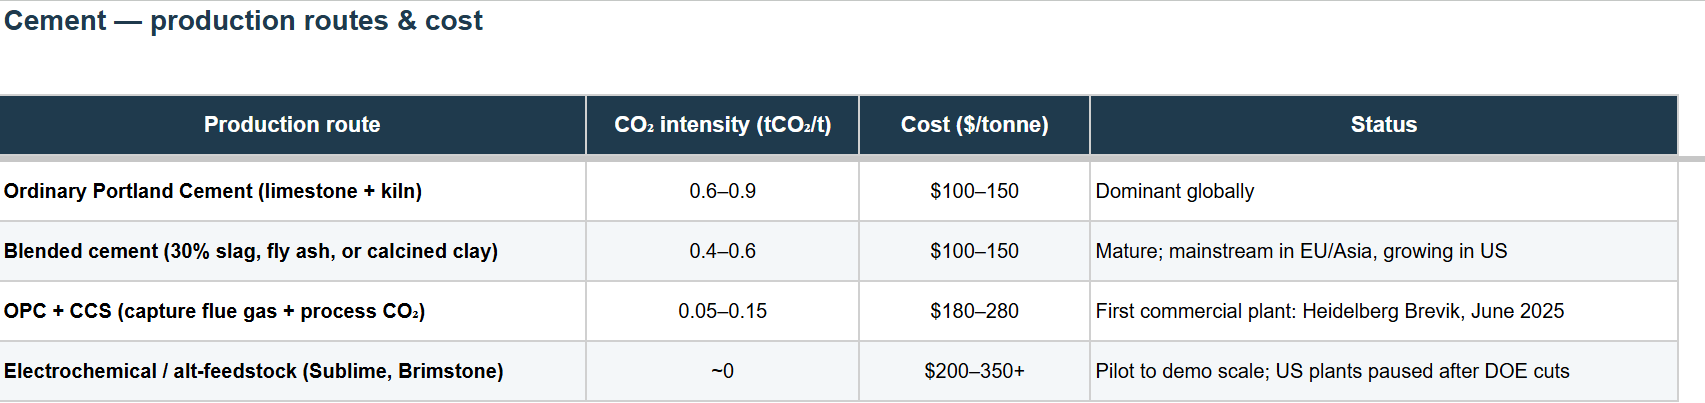
Green premium: roughly 60-150% over OPC. On a finished house, the embodied-cost impact is modest (low single-digit percent of total), but on the manufacturer’s P&L it’s destructive without a carbon price.
Steel
Global production ~1.85 Gt/year. Ranges reflect US and EU producer economics; numbers diverge in lower-cost geographies like China and India.
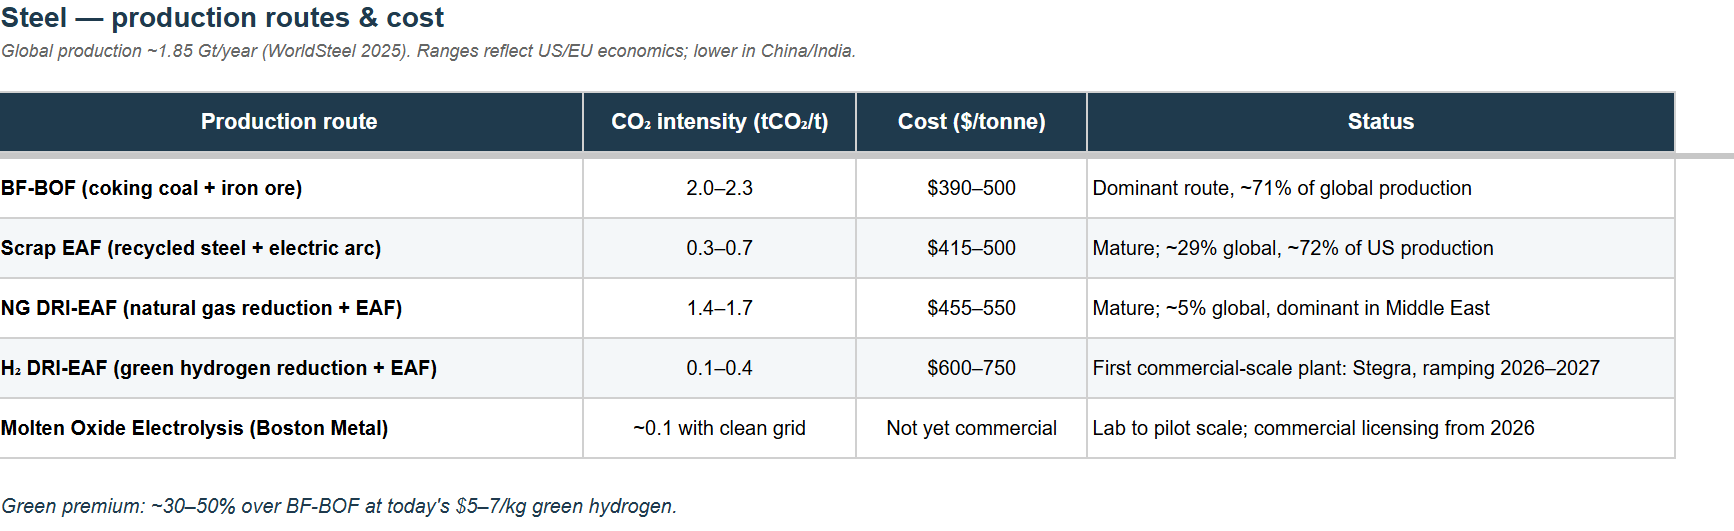
Green premium: ~30-50% over BF-BOF at today’s $5-7/kg green hydrogen costs. Studies project parity when green H2 hits ~$1.5/kg, which is at least a decade out at current trajectories. Without a carbon price, the cheapest route wins, and the cheapest route is still the coking-coal blast furnace in low-energy-cost regions.
Ammonia
Global production ~185 Mt/year, dominantly for nitrogen fertilizer (which feeds about half the planet). Costs swing hard with natural gas prices.
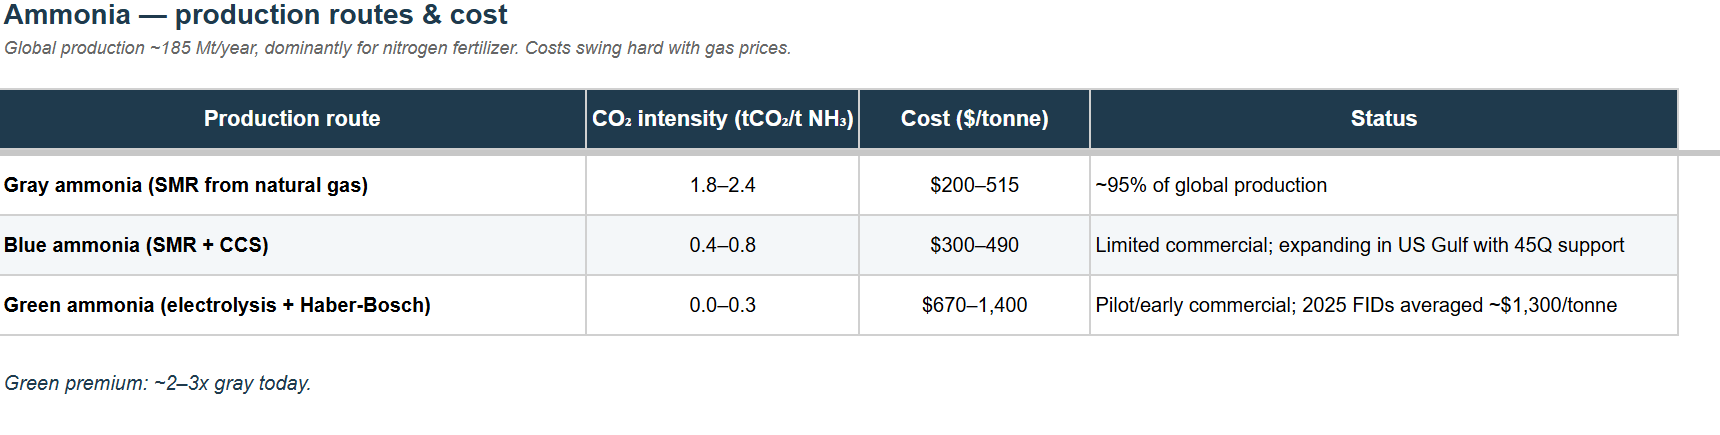
Green premium: ~2-3x gray today. Blue ammonia is the more interesting near-term lever in the US given 45Q survived the OBBBA, and SMR with CCS reuses all existing infrastructure essentially.
Ethylene (the gateway petchem)
Global production ~200 Mt/year. Feedstock determines almost everything: US/Middle East run on ethane (cheap, from gas processing), Europe/Asia run on naphtha (more expensive, from oil refining).
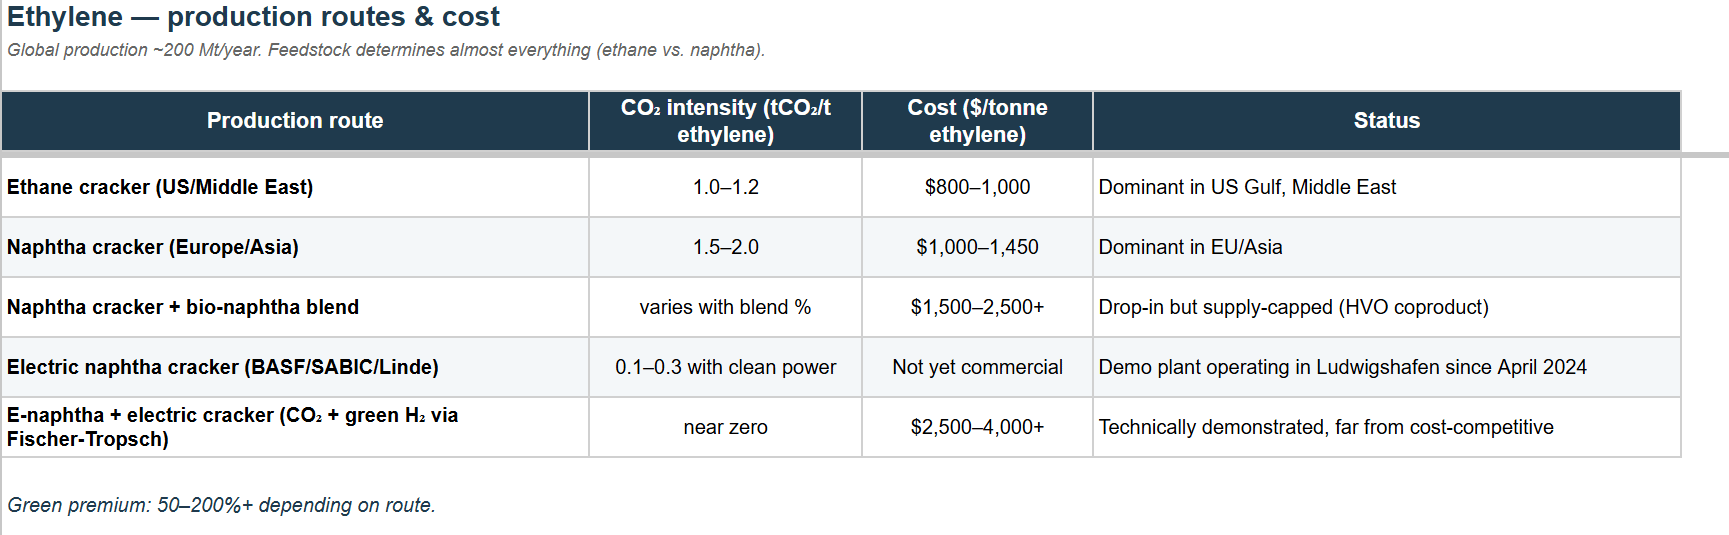
Green premium: 50-200%+ depending on route. And the harder problem isn’t the cracker emissions; it’s the feedstock carbon (the carbon atoms that become the plastic). Truly decarbonized plastics need bio- or CO2-derived feedstocks, both of which face supply or cost ceilings.
It’s expensive, for now
The conventional process is cheap, mature, fully amortized, and operates at scale. The low-carbon alternatives are technically possible but carry a 25-150% price premium that the international commodity market has no obvious way to absorb. And it’s important to note that CCS is also more expensive than the current dominant production methods. It just happens to be less expensive than the other low-emission alternatives.
This is fundamentally different from the solar-vs-coal story, where the new technology eventually undercut the old one on a $/MWh basis and won on its own merits. In the commodity industry, the new technology hasn’t crossed under, and at current trajectories it won’t for another decade or two without help. “Help” means policy. It means a carbon price, a border adjustment, public procurement, a regulated standard, or some combination. The EU’s CBAM is the most serious attempt anyone has made to use trade policy to close this gap. The US currently has no equivalent.
Without that policy scaffolding, every importer-of-record in every commodity chain rationally buys the cheapest ton, and the cheapest ton is still the high-carbon one.
The Near-Term
If you tune out the technologies that might be transformative in 15-20 years and focus on what could actually bend the curve in the next decade, the list is unsexy but real:
Low-temp heat electrification. Heat pumps in food, paper, light chemicals, district heat.
Natural gas DRI-EAF for steel. Switching a blast furnace to natural-gas-based DRI feeding an electric arc furnace cuts emissions by ~30-40% today (and then deeper if you swap in hydrogen later, which is the Stegra play). The US steel industry is already ~72% EAF in 2024, which is why US steel emissions per ton are well below the global average.
Recycling. EAF steel from scrap is ~70-80% less emissions-intensive than primary BF-BOF steel. Recycled aluminum uses ~95% less energy than primary. Plastics recycling is comparatively dismal but improving. Recycling has the advantage of being mature, profitable, and indifferent to the rest of the energy system.
CCS on the highest-concentration emitters. Cement, ammonia, ethanol, and gas processing all produce CO2 streams with concentrations>20% (much easier to capture than dilute power plant flue gas). Heidelberg Materials officially opened its Brevik plant in Norway in June 2025 ( with a capacity of capturing up to 400,000 t/y although now it is only capturing 100,000t/y), making it the world’s first industrial-scale CCS cement facility. The Mitchell, Indiana Heidelberg plant was meant to be the US first; its $500M DOE OCED award was also canceled in 2025. The technology works, but the financing requires a credit (45Q in the US, an ETS price in Europe).
Blended cements and alternative binders. Cement that’s 30% slag or 30% fly ash is already mainstream in much of the world, and is the single biggest near-term abatement lever in cement.
Each item is in the single-digit-percent-reduction range globally, but stacked, they get you meaningfully along.
The Hydrocarbons Don’t Disappear
Here’s a fact that climate-policy conversations consistently underweight: even the most aggressive credible net-zero scenarios keep significant oil and gas production through 2050. The IEA’s Net Zero Emissions by 2050 (NZE) Scenario, the most demanding pathway in the agency’s library, calls for global oil demand to fall ~75% to 24 million barrels per day by 2050 (from ~100 mb/d today), and natural gas to fall ~55% to ~1,750 bcm. Those are massive declines. They are also not zero. The Announced Pledges Scenario (APS), which assumes countries meet their stated climate commitments, is gentler still: oil at 55 mb/d and gas at 2,400 bcm by 2050. The new Current Policies Scenario in WEO 2025 (no further climate action) projects oil production to grow to 113 mb/d.
The interesting question is what the remaining barrels are used for. In NZE:
About 70% of remaining 2050 oil demand is petrochemical feedstock plus other non-combustion uses (asphalt, bitumen, lubricants). The carbon atoms in the oil become products rather than flue gas. Non-energy use rises from ~17% of total oil consumption in 2021 to ~72% by 2050.
About two-thirds of remaining natural gas use in 2050 is paired with CCS. Gas survives in the model precisely because it can be attached to capture for hard-to-abate industrial heat, blue hydrogen, and ammonia.
Refineries shift away from gasoline and diesel and toward petrochemical feedstocks and specialty products. The mix at the top of the barrel changes more than the volume.
This is the central point of this post translated back into the O&G value chain: the energy transition isn’t principally a decline in oil and gas production. It’s a re-composition of demand from combustion to chemistry, and from unabated to capture-bound. The marginal barrel in any 2050 scenario consistent with net zero goes into a steam cracker, a fertilizer plant, or a refinery making petchem precursors. The marginal cubic meter of gas powers a steel mill or an ammonia plant with CCS strapped on the back.
This also reframes the factors that determine fossil demand trajectories. Power-and-transport demand for hydrocarbons collapses in any net-zero pathway (that’s the easy part). Industrial demand bends slowly, with the curve set by exactly the technologies and policies described above (hydrogen DRI, electrochemical cement, CCS, electrification of low-temp heat, bionaphtha and e-naphtha for chemicals).
It also reframes the political conversation. “End fossil fuels” or “CCS doesn’t work so don’t do it” is a much harder slogan to operationalize than it sounds, because no credible net-zero pathway actually ends fossil fuels. It ends combustion of fossil fuels at scale. The hydrocarbons that remain, and the wells, pipelines, refineries, and crackers that produce and process them, are the part of the O&G system most tightly coupled to physical industry.
What Needs To Change
The binding constraints on industrial decarbonization aren’t primarily technical; they’re commercial. They show up at three layers:
Demand side. Someone has to pay the green premium. Microsoft, Apple, Stripe, Google, Amazon, and (recently) the European auto industry have begun entering into offtake agreements for low-carbon cement, steel, and chemicals. Public procurement (federal buildings, infrastructure bills with Buy Clean provisions) is a bigger lever, but it is mostly stalled in the US. Without a buyer, there’s no revenue.
Policy side. An effective policy is a carbon price applied at the border (so domestic decarbonization isn’t undercut by imports). The EU’s CBAM (Carbon Border Adjustment Mechanism) is the world’s first real test, fully phasing in 2026-2034. The US has nothing equivalent, and the second Trump administration has actively pulled back the IRA tools that were designed to underwrite industrial decarbonization: 45V (clean hydrogen) scaled back in the One Big Beautiful Bill Act of July 2025; DOE OCED grants for cement, hydrogen hubs, and CCS canceled or paused; EPA’s methane Waste Emissions Charge implementing rule repealed by Congress in March 2025.
Capital side. Industrial decarbonization is capital-intensive infrastructure. It requires long-duration capital that’s tolerant of technology risk. Patient capital is starting to show up (Wallenberg, Hy24, Just Climate, Breakthrough Energy Ventures, TPG Rise), but the gap between what’s needed (~$1-2T globally by 2050, per IEA) and what’s flowing remains enormous.
The truth is that the renewables-and-EVs story worked because it eventually aligned with private commercial economics. Solar got cheaper than coal. EVs got cheaper to operate than gasoline cars. Industrial decarbonization, with rare exceptions, doesn’t yet have that property. It needs policy to bridge the gap until it does, and the US is currently dismantling that bridge.
Same Story, Different Day
The fundamental flaw in the ProPublic/Drilled article is not that they are wrong that CCS has failed to deploy at the scales modeled, or written about in academia. They are wrong on plenty, including the conflation of CCS and CDR, the assertion that enhanced oil recovery doesn’t have stringent regulation, the idea that we are CO2 storage limited, and so on.
The flaw is that they are incurious. They didn’t think, or didn’t want, to answer the two questions which are most important:
1. Why has CCS failed to deploy at scale?
2. What are the alternatives to CCS in the sectors the models say we need CCS, and how do we decarbonize those sectors without CCS?
The answer to question one is that CCS hasn’t been adequately incentivized through policy and regulation. It is also because we, as a globe, do not value reductions in carbon as much as we do CCS costs.
The answer to the second is….we don’t! We simply cannot hit net-zero in the short- to medium-term without CCS. Which is why I frequently point out that these authors and the rest of the anti-CCS contingent should really hope we deploy CCS at scale. Because at the moment the alternative is for those industrial emissions to continue entering the atmosphere while we work on scaling up non-fossil alternatives. And then we need even more, even more costly but necessary carbon removal to draw down all that CO2 we could have been capturing in the first place!
Solar, wind, batteries, virtual power plants, demand response, efficiency, heat pumps are all great. They will be the backbone (along with geothermal, nuclear, and hydro) of power sector decarbonization. However, they will not meaningfully decarbonize industry in the short- to medium-term, solely because they cannot, physically and economically.
Glossary
BF-BOF: Blast Furnace – Basic Oxygen Furnace. The dominant primary steelmaking route; uses coking coal as both fuel and reductant.
DRI: Direct Reduced Iron. Iron produced by reducing iron ore with gas (natural gas today, hydrogen in green steel).
EAF: Electric Arc Furnace. Steel furnace that melts scrap or DRI using high-current electric arcs.
OPC: Ordinary Portland Cement. The standard binder that holds the modern world together.
SCM: Supplementary Cementitious Material. Slag, fly ash, calcined clay, or similar; replaces some clinker in concrete.
MOE: Molten Oxide Electrolysis. Boston Metal’s electrochemical iron-making process.
HVO: Hydrotreated Vegetable Oil. The dominant route to renewable diesel and SAF; bionaphtha is a coproduct.
CCS / CCUS: Carbon Capture (Utilization) and Storage.
CBAM: Carbon Border Adjustment Mechanism. The EU’s carbon-price-at-the-border tool, phasing in 2026-2034.
OCED: Office of Clean Energy Demonstrations. The DOE office responsible for industrial demo grants.
OBBBA: One Big Beautiful Bill Act. The July 2025 tax bill that scaled back IRA clean-energy provisions.
VRE: Variable Renewable Energy. Solar and wind, the resources whose output varies with weather and time of day.
NZE: Net Zero Emissions by 2050 Scenario. The IEA’s most aggressive decarbonization pathway.
APS: Announced Pledges Scenario. The IEA scenario that assumes governments hit their stated climate commitments.
mb/d: Million barrels per day. Standard unit for global oil demand and supply.
bcm: Billion cubic meters. Standard unit for natural gas volumes.
I think this is the best article on this topic I've ever read
Very interesting and stimulating read! Quick question on the CO2 coming from the SMR: Maybe I am missing something obvious here, but it seems like the CH4 + H2O → CO + 3H2 + CO2 does not add up. Is something like CH4 + 2H2O → 4H2 + CO2 correct? Apologies if there is a misunderstanding on my side.